ServicesFinancial Advising
Financial Advising in Manalapan
We sit down with you, at our office or by phone and video, and work through the money decisions in front of you. Rollovers, savings, a new job, an inheritance. We look at the small details too, like account titles and beneficiary forms, because they often decide how well a plan holds up.
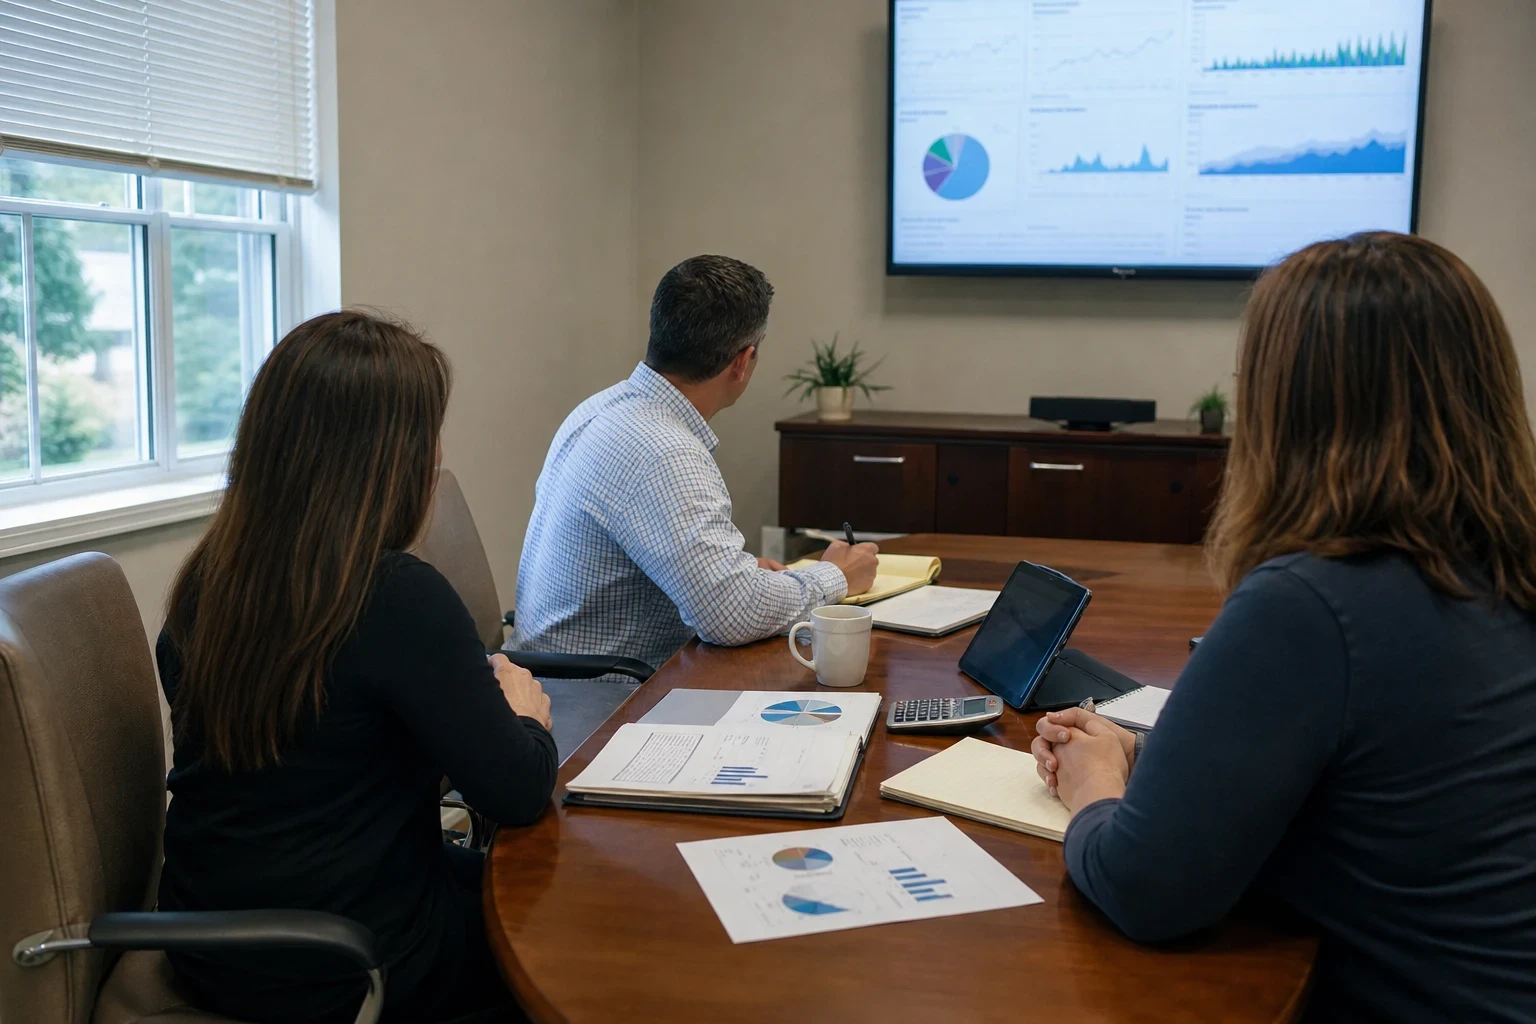
Advice for the decision you are facing now
Financial advising is the ongoing conversation behind good money decisions. You bring a question, such as whether to roll over an old 401(k), how much cash to keep on hand, or what to do with a bonus, and we give you a clear answer with the reasoning laid out. It sits alongside Financial Planning, which maps the whole picture, and Investment Management, which handles the portfolio day to day.
We are Series 7, Series 66 and SIE licensed, and that training shows most in the quiet parts of the work: reading a fund's expense ratio correctly, checking whether a transfer will move in kind or be sold to cash, and spotting a beneficiary form that was never updated after a marriage.
Most clients come to us from Manalapan and nearby towns like Marlboro, Freehold and Monroe, and many meet with us by video once the first conversation is done.
What our advising work covers
- A review of every account
- We go through statements for your brokerage accounts, IRAs, workplace plans and savings. We note fees, holdings that overlap, and cash sitting idle.
- Beneficiary and titling check
- We confirm who is named on each account and how each one is titled. These forms override a will, so a stale one can send money where you never meant it to go.
- Rollover and transfer guidance
- When you change jobs or consolidate accounts, we walk through the options and the order of steps. The goal is to avoid an accidental taxable distribution or a missed deadline.
- Answers between meetings
- Questions do not wait for an annual review. When something comes up, a raise, a home sale or an offer of company stock, we talk it through with you by phone.
- Written recommendations
- After each meeting you get a short written summary of what we discussed and what we suggest, so you can review it with your spouse or your accountant.
Signs it is time to talk with an advisor
Old 401(k)s from past jobs
Accounts left behind at former employers are easy to lose track of. They often carry higher fees and investment choices you no longer remember making.
A big change in your life
Marriage, divorce, a new child or the loss of a parent all touch your accounts. Each one is a reason to check beneficiaries and goals.
Cash with no plan
A large sum in checking after a sale, bonus or inheritance tends to sit there. We help you decide what it is for before deciding where it goes.
You are not sure what you pay
If you cannot say what your funds and accounts cost each year, that is worth finding out. Small percentage fees add up over long periods.
Conflicting advice
Coworkers, relatives and headlines rarely agree. A calm second look at your own numbers usually settles the question.
How working with us unfolds
- 1
An introductory meeting
You reach us by phone and we set a time to talk, at our office or by video. We learn what prompted the call and explain how we work and how we are paid.
- 2
Gathering the paperwork
We ask for recent statements, workplace plan details and any beneficiary forms you have. Nothing moves at this stage; we are only reading.
- 3
Findings and recommendations
We meet again to go through what we found, line by line. You see the reasoning behind each suggestion and decide what, if anything, to act on.
- 4
Follow-through and check-ins
If you go ahead, we handle the forms with you and confirm each transfer lands as intended. After that we stay in touch as your situation changes, and bring in Retirement Planning or Tax Management when a question calls for it.
What shapes the cost of advising
We explain exactly how we are compensated during the introductory meeting, before you commit to anything. The cost depends on how much work your situation needs and how often you want us involved.
- Number of accounts
- Reviewing two accounts is a different job from untangling a dozen spread across old employers and institutions.
- Complexity of the questions
- Stock options, a business you own or a recent inheritance take more analysis than a single rollover.
- One-time or ongoing
- Some clients want advice on one decision. Others want a standing relationship with regular reviews, which is structured differently.
- Coordination with other professionals
- Working alongside your accountant or estate attorney takes added time, and it is often where the most useful details surface.
Questions about financial advising
Something not covered here? (732) 696-7347
How is financial advising different from financial planning?
Advising focuses on specific decisions as they come up and on keeping your accounts in good order. Financial Planning builds a full written map of your goals, cash flow and timelines. Many clients start with advising and move into a full plan later.
Do I need a certain amount saved to work with you?
We are glad to talk with anyone who wants careful advice about their money. The introductory meeting is the place to see whether our work fits what you need. If it does not, we will say so plainly.
Will you pressure me to move my accounts or buy something?
No. We show you what we found and why we suggest a change, and we tell you how we are paid for any recommendation before you act. Sometimes the right advice is to leave things as they are.
Is an office visit required, or can we talk remotely?
An office visit is never a requirement. After that first conversation, plenty of our clients prefer a video call or a phone appointment that fits around work and family. We share your statements on screen and walk through them together, page by page.
What should I have ready for the first meeting?
Bring whatever is handy: recent account statements, workplace retirement plan details and a sense of what is on your mind. If something is missing, we will tell you what to look for afterward.
Start with one honest conversation
Tell us what is on your mind and we will tell you how we would approach it. Clients across Manalapan and the surrounding area begin with a single phone call.